NEMT Insurance
Quick Answer
Understand how NEMT auto, general and professional liability address vehicle and passenger-assistance exposures. Have Casurance review your coverage gaps.
A passenger claim can begin at the curb, inside the van or at a facility doorway. Casurance helps you examine where your auto, general liability and professional liability policies meet before you rely on them for a healthcare transportation contract.
Understand what each coverage does
The same coverage questions matter for a single wheelchair van, a small mixed-service fleet and a large NEMT company. Our program review scales to your vehicle count, staffing, assistance practices and contract obligations.
Review My Coverage Gaps · 1-888-254-0089
Two-step request: save business and contact details, then add operations, coverages, vehicles, drivers and documents.
Commercial auto: the moving vehicle and more
For-hire medical transportation belongs on a policy that accepts the declared use. Review liability limits, covered-auto symbols, scheduled vehicles, drivers, service radius and loading or unloading provisions. Uninsured and underinsured motorist coverage and medical payments are separate selections subject to state rules and availability; they are not substitutes for liability coverage.
General liability and professional services
General liability can address covered premises and non-auto bodily injury or property damage allegations. Professional liability may respond to covered errors in declared assistance services. A wheelchair securement or passenger-transfer allegation can raise auto-use, professional-services and other exclusions. Ask the agent to examine the wording together; do not assume every passenger injury belongs to a single automatic passenger-liability policy.
Protect the equipment that makes your van useful
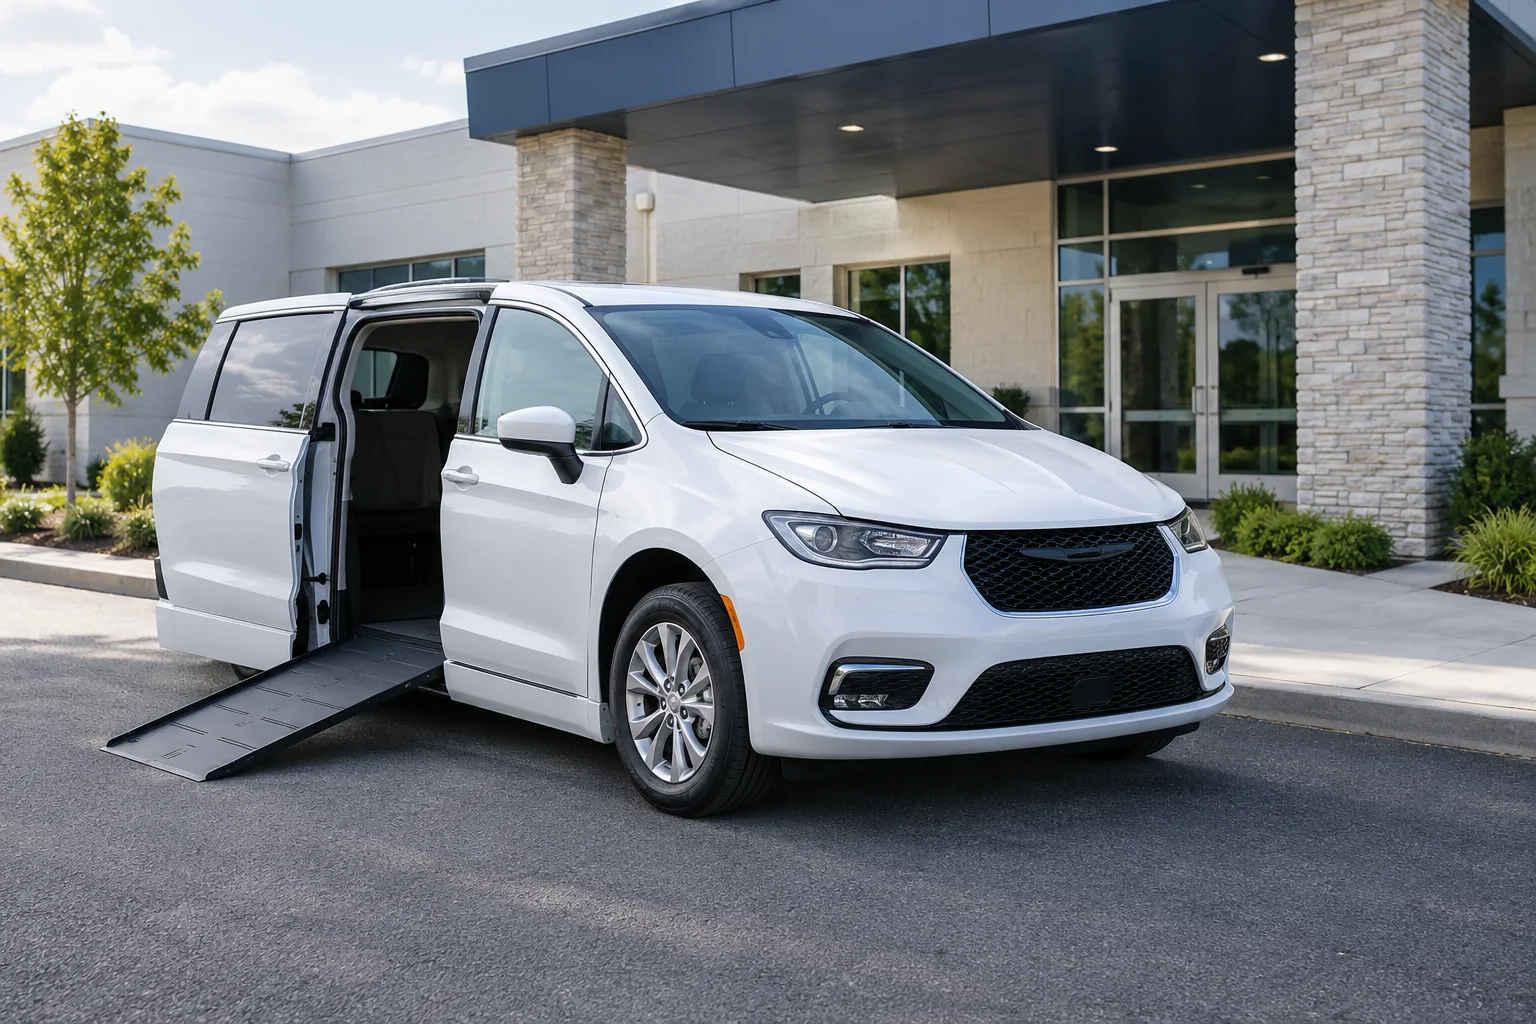
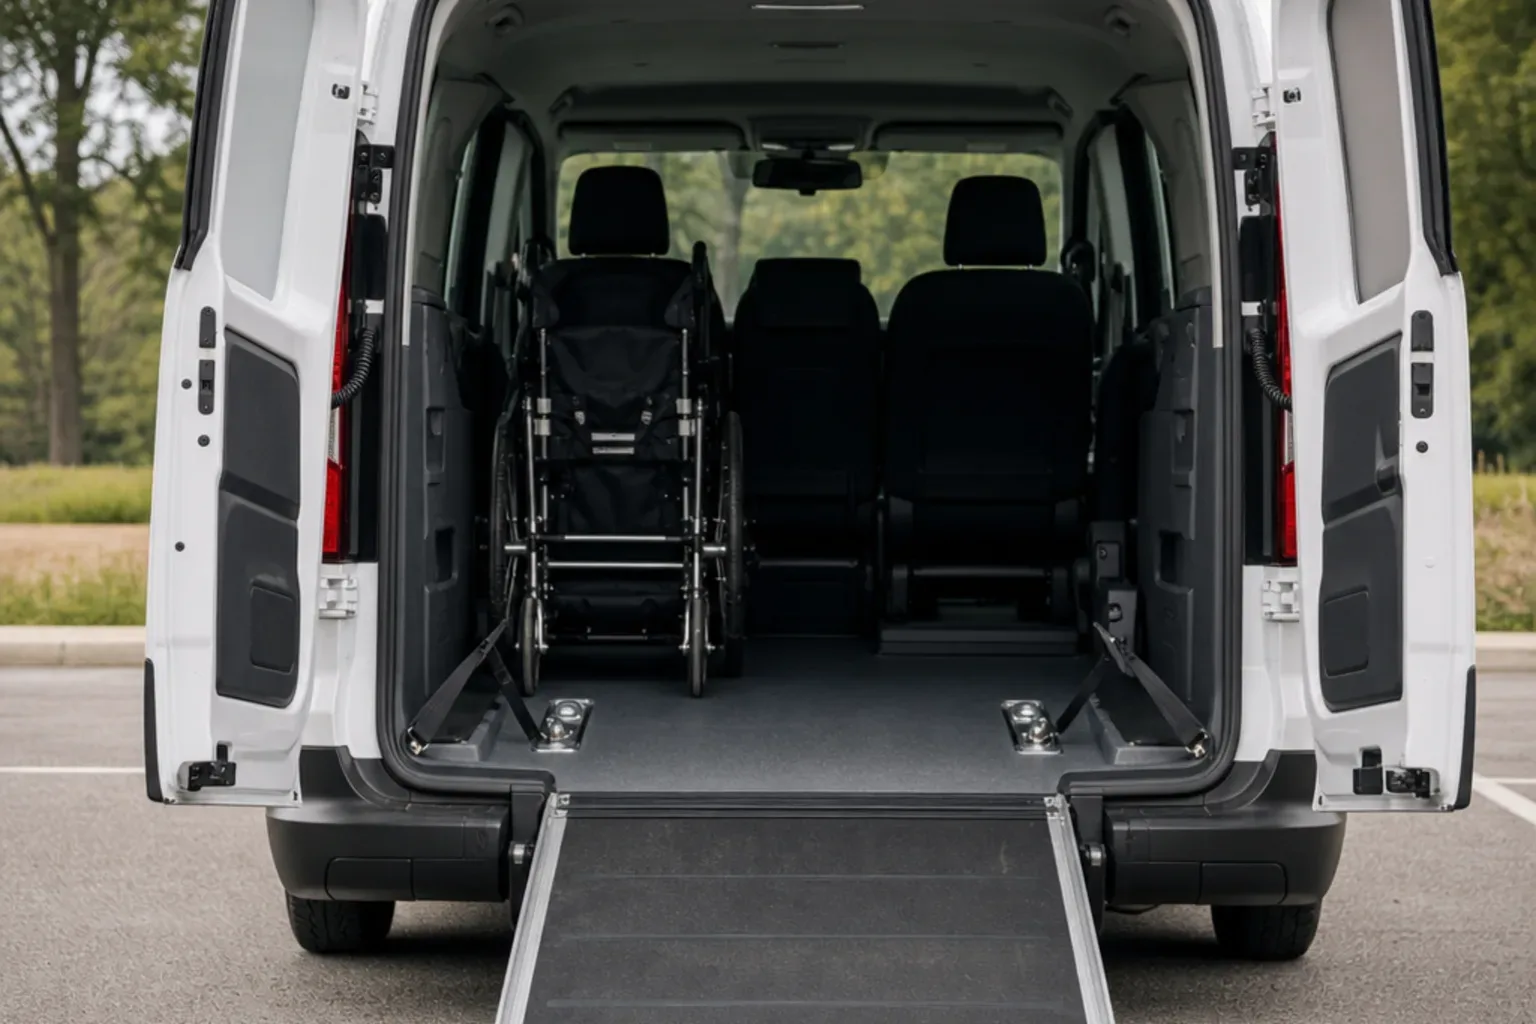
Wheelchair lifts, ramps, restraint systems and stretcher securement can represent substantial conversion costs. Provide invoices, photographs and values so physical damage review includes installed equipment. Portable medical equipment, supplies and passenger-owned mobility devices may require different treatment from the vehicle itself. Discuss deductibles, valuation and any available rental or downtime option before a repair interrupts service.
People, privacy and the business premises
Consider workers’ compensation for employee injuries, SAM for covered abuse or molestation allegations, and cyber coverage for dispatch or passenger-data incidents. A leased dispatch office, waiting area or maintenance space also creates property and general liability exposures. Crime and employee dishonesty coverage can be relevant when staff handle fares or business funds. Insurance does not replace privacy, hiring or passenger-safety controls.
Excess limits and vehicles you do not own
Umbrella or excess coverage should identify the correct underlying policies. It may not extend over professional liability or SAM unless specifically arranged. Hired and non-owned auto requires a separate look at rentals, replacement vans, employee-owned cars and subcontracted providers. A broker’s request for $5 million of total liability, for example, should be checked against the actual underlying and excess structure.
California documentation versus contract limits
DHCS provider-application guidance lists a commercial liability enrollment threshold of $100,000 per claim and $300,000 annual aggregate. That enrollment item is not a statement of the commercial auto limit your operation or broker contract needs. Send both the enrollment instructions and the buyer’s insurance exhibit for comparison. Source: DHCS medical transportation provider application information.
An Orange County facility pickup example
Illustrative exposure: while collecting a rehabilitation passenger, a driver’s equipment damages the facility entrance and the passenger alleges an assistance injury. The facts, equipment ownership and policy exclusions determine which coverage may respond. Casurance can use your actual loading procedure and facility agreement to identify the questions to resolve at quotation.
Questions about understand what each coverage does
Does physical damage automatically cover my conversion cost?
Do not assume it does. Show the carrier how the van is equipped and how its value was determined, and confirm any equipment limits or exclusions in the proposal.
Is a certificate enough to add a hospital as an additional insured?
No. A certificate reports coverage; the applicable policy endorsement grants any additional-insured rights. The requested legal entity and wording need review.