Business owner and contractor discussing operations outside a retail business
Commercial General Liability Coverage

General Liability Insurance in Los Angeles, CA

General liability insurance helps protect your business if a customer, client, vendor, landlord, or other third party claims your business caused injury, property damage, or personal and advertising injury. Casurance helps business owners compare coverage options, limits, certificates, endorsements, and related policies like BOP, workers' compensation, commercial auto, professional liability, and umbrella insurance.

  • Helps respond to covered third-party injury and property damage claims
  • Can help pay legal defense costs, settlements, or judgments
  • Often required by landlords, clients, vendors, and project owners
  • Coverage options for contractors, property owners, restaurants, retail, offices, and service businesses

Licensed in California, Texas, Nevada, and all 50 states.

CASURANCE · BUSINESS INSURANCE

Get Your Free Quote

Start with your contact details. No payment or commitment required.

Open the full-page quote application

Step 1 of 3 — Get started

  1. 1Get started
  2. 2Your business
  3. 3Coverage, review & submit

Your answers are kept in this browser while you complete your request.

Import information from a document

Upload a PDF, spreadsheet, Word file, text file, or image — or paste text directly. We will suggest fields for you to review before applying.

PDF, CSV, Excel, Word, TXT, JPG, or PNG · up to 5 files

Review suggestions before applying. Only empty fields are filled; existing answers and requested limits are kept. Attach documents for your agent at the end of the application.

Casurance saves your quote progress so our team can help you complete your request.

One application. Five directly appointed carrier partners.

Travelers logo

Travelers

Chubb logo

Chubb

CNA logo

CNA

AmTrust logo

AmTrust

Berkshire Hathaway GUARD logo

Berkshire Hathaway GUARD

Travelers · Chubb · CNA · AmTrust · Berkshire Hathaway GUARD. Availability depends on your business and underwriting.

Coverage built around your next move

Get your business ready for the next opportunity.

Winning work is only part of the job. Let Casurance help you review the general liability protection your operations, customers and contracts call for. Start with your contact details, then tell us about your business in the existing application.

Contractor preparing for a business project

A new job. A new client. A new requirement.

Bring us the insurance requirements before work starts. Tell us what your business does, where you work, and whether you use subcontractors. We can review the requested limits and endorsements with your submission.

Business representatives reviewing insurance documentation

A lease or contract asking for proof of insurance?

Have the certificate holder details and insurance section of your agreement ready. A certificate shows evidence of coverage; it does not itself add coverage or change your policy. Ask about any additional insured or other endorsement requirements.

Business owner reviewing coverage documents

Renewing? Compare more than the price.

Share your current policy and the changes in your operations. Review limits, exclusions, covered activities and contract requirements alongside the premium. Tell us your requested start date so the team can understand your timeline.

A focused quote request

Tell us what you need. Give us the details to shop it.

Whether you are opening a business, taking on a contract or reviewing a renewal, a clear submission helps our team understand the account. You can request coverage and upload supporting documents through the application.

Speak with Casurance

Have these details handy

  • Your business activities and where you operate
  • Annual sales, payroll and employee information
  • Requested coverage limits and start date
  • Current policy, loss history and contract requirements

Submitting an application does not bind coverage. Options, terms and pricing depend on carrier review and underwriting. Review the policy and endorsements before making a decision.

What Is General Liability Insurance?

General liability insurance, also called commercial general liability or CGL, is one of the main policies most businesses buy first. It helps protect your business from common third-party claims, including customer injuries, damage to someone else's property, and certain lawsuits involving your advertising or business operations.

This coverage is different from workers' compensation, commercial auto, professional liability, cyber liability, and commercial property insurance. General liability is mainly for claims from people outside your business, not your own employees or your own property.

Simple way to think about it

If someone outside your business gets hurt, their property gets damaged, or they sue you over covered advertising or business operations, general liability may help respond.

Small business owner reviewing general liability insurance coverage on a tablet
Restaurant with safe operations covered by general liability insurance

What General Liability Insurance Covers

A standard general liability policy may help respond to several common types of third-party claims.

Bodily Injury

A customer slips in your store, a visitor falls at your office, or someone is injured because of your business operations. General liability may help pay medical costs and legal defense expenses if your business is legally responsible.

Property Damage

Your employee accidentally damages a client's wall, floor, window, equipment, furniture, or other property while working. General liability may help pay repair or replacement costs.

Personal & Advertising Injury

A competitor, customer, or third party claims your advertisement, website, social media post, or marketing material caused harm, such as libel, slander, copyright infringement, or false advertising.

Legal Defense Costs

If a covered claim turns into a lawsuit, the policy may help pay attorney fees, court costs, settlements, or judgments, subject to policy terms, conditions, exclusions, and limits.

Medical Payments

Some policies include limited no-fault medical payments for minor injuries to non-employees, even before a lawsuit happens.

Products & Completed Operations

If a product you sold or work you completed later causes injury or property damage, products-completed operations coverage may help respond depending on the facts and policy wording.

Real-Life General Liability Claim Examples

These scenarios show how general liability insurance may help real businesses respond to covered claims.

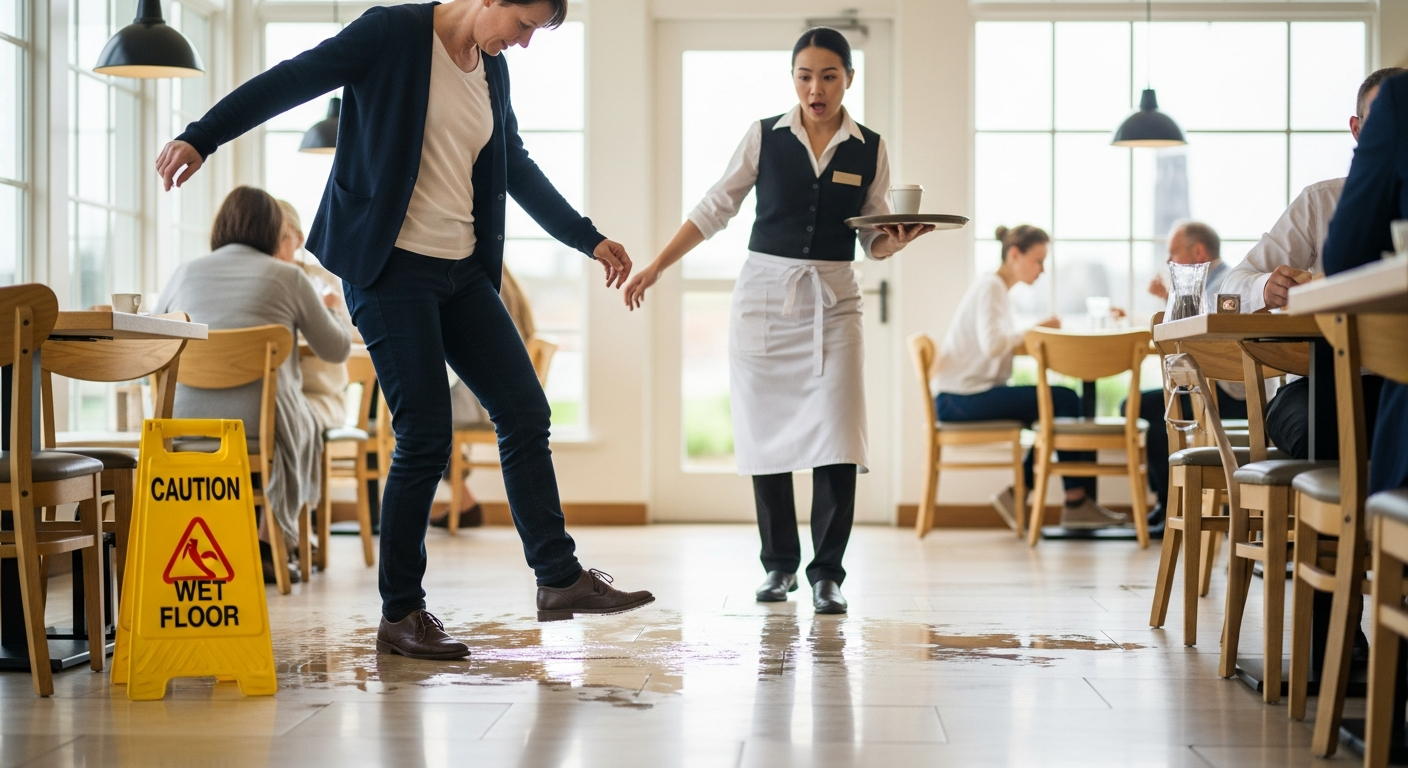
Customer slip and fall claim covered by general liability insurance

Restaurant slip and fall

A customer slips near the drink station and needs medical care. General liability may help with medical payments and legal defense if the customer sues.

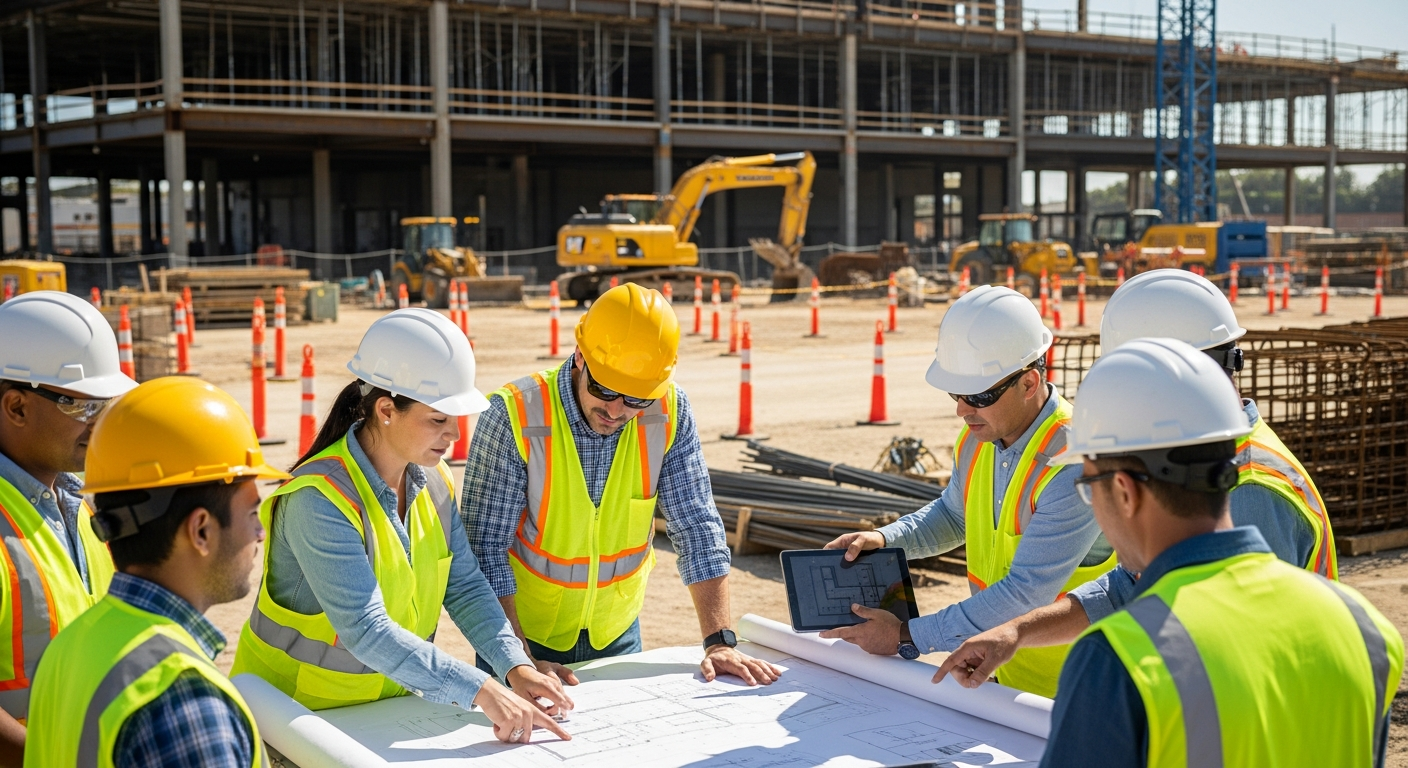
Contractor team at job site with general liability insurance coverage

Contractor property damage

A plumber, painter, electrician, handyman, or flooring contractor accidentally damages a customer's wall, floor, pipe, or fixtures while working. General liability may help pay repair costs and defense expenses.

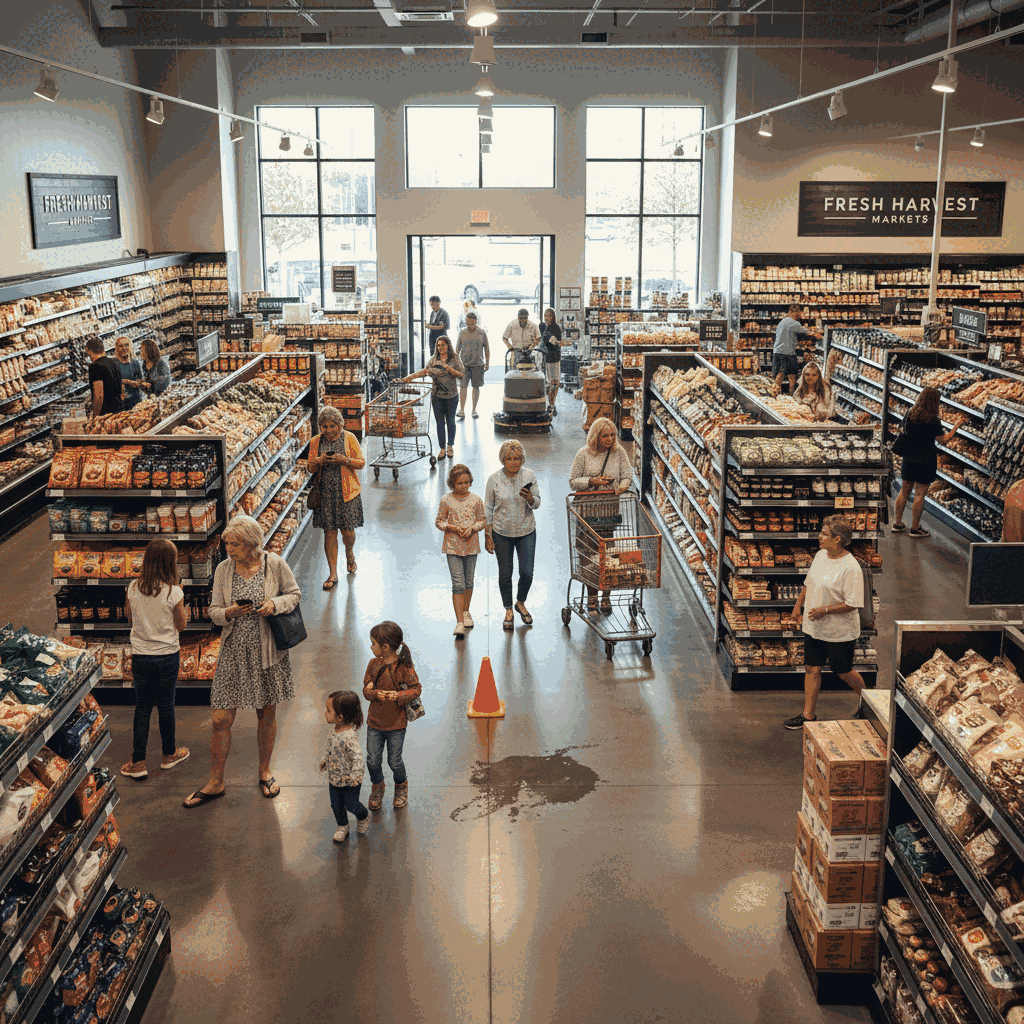
Retail customer injury claim covered by general liability insurance

Retail customer injury

A shopper trips over a display, box, mat, or uneven flooring. General liability may help cover the claim if the business is legally responsible.

Advertising injury claim and general liability insurance coverage

Advertising injury

A business uses an image, slogan, or marketing message and another company claims copyright infringement, libel, slander, or false advertising. General liability may help with covered defense costs.

Completed operations coverage under general liability insurance

Completed work issue

A contractor finishes a job, and later the completed work causes damage or injury. Products-completed operations coverage may apply depending on the policy.

Property owner liability covered by general liability insurance

Property owner or landlord claim

A visitor is injured at an apartment building, shopping center, office building, or vacant property. General liability may help protect the owner, landlord, or property manager from covered third-party claims.

Who Needs General Liability Insurance?

Most businesses that work with clients, sell products, rent space, advertise, visit job sites, own or manage property, or allow customers onto their premises should consider general liability insurance.

You may need general liability insurance to sign a lease, bid on a job, work with a client, get a permit, satisfy a landlord, or show proof of coverage through a certificate of insurance.

Contractors and subcontractors
Restaurants, cafés, food trucks, bars, and caterers
Retail stores and e-commerce sellers
Janitorial and cleaning companies
Landscapers and trades
Consultants and professional offices
Real estate owners and property managers
Beauty salons, barbers, spas, and fitness studios
Hotels, motels, and hospitality businesses
Apartments, HOAs, condo associations, and mobile home parks
Schools, daycares, camps, and religious organizations
Manufacturers, distributors, and wholesalers
Security guard and detective agencies
Shopping centers, office buildings, and LRO properties

Business Classes We Can Help With

Casurance helps business owners review general liability options for small business, contractor, premises, habitational, hospitality, retail, office, service, and transportation-related risks.

General liability is often required before a contractor can bid, start work, pull permits, or access a job site. Casurance can help contractors review limits, additional insured wording, waiver of subrogation, primary and non-contributory requests, completed operations requirements, and certificate requests.

General Contractor (GC)
Carpet & Flooring Installation
Carpet Cleaning
Concrete Work
Debris Removal
Drywall Installation
Electrical Contractors
Excavation
Fencing Installation
Flooring Installation
Framing
Grading
Guniting
HVAC Installation
Insulation Installation
Janitorial Services
Landscaping
Masonry
Metal Erection
Painting Contractors
Paving
Plastering
Plumbing Contractors
Refrigeration
Remodeling
Roofing Contractors
Sandblasting
Septic System Installation
Siding Installation
Sign Installation
Solar Installation
Swimming Pool Contractors
Tile Installation
Window & Door Installation
Welding
Cabinet Installation
Demolition
Waterproofing
Stucco Application
Gutter Installation

Don’t see your class? Contact us — coverage options may be available, subject to underwriting approval.

Class codes, eligibility, rates, forms, and exclusions vary by program and underwriting review. Casurance can help review your operations and match your business with available general liability options.

Not every class is available in every state or with every insurance program. Eligibility, pricing, forms, exclusions, and endorsements depend on underwriting approval.

Not every class is available in every state or with every insurance program. Eligibility, pricing, forms, exclusions, and endorsements depend on underwriting approval.

Coverage Options and Endorsements Businesses Often Ask For

Contracts often ask for more than a basic general liability policy. Casurance can help review insurance requirements from landlords, project owners, general contractors, vendors, and clients so your coverage and certificates match what is being requested.

Additional insured
Waiver of subrogation
Primary and non-contributory wording
Products-completed operations
Contractual liability
Damage to premises rented to you
Owners and contractors protective coverage
Project-specific general liability
Railroad protective liability
Liquor liability
Abuse and molestation coverage where applicable
Hired and non-owned auto
Umbrella or excess liability

Need a Certificate of Insurance?

A certificate of insurance, or COI, is proof that your business has active insurance coverage. Landlords, project owners, vendors, property managers, and clients often request a COI before allowing work to begin.

  • Additional insured requests
  • Waiver of subrogation requests
  • Primary and non-contributory wording
  • Project owner or landlord requirements
  • Contract insurance requirement reviews
  • General contractor or vendor compliance requests
Certificate of insurance for general liability coverage
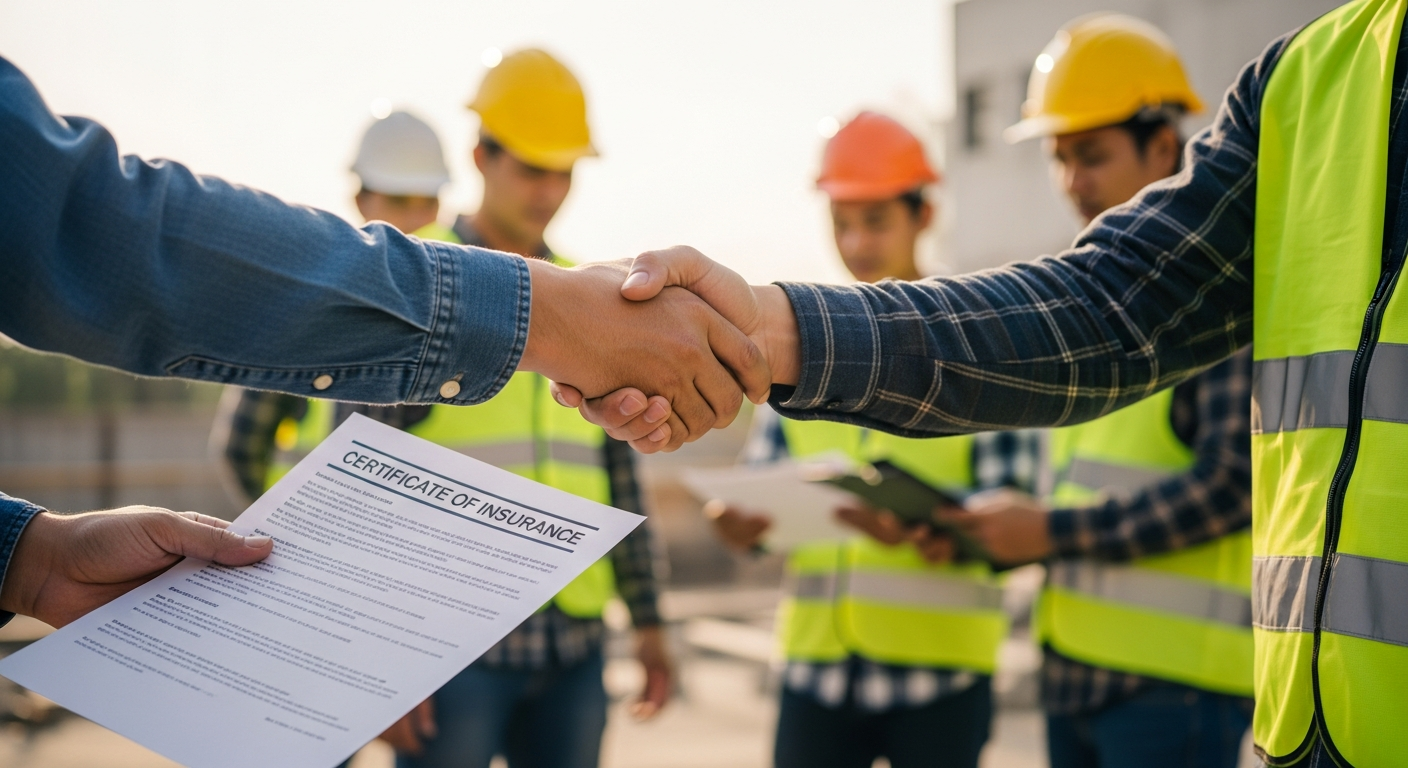
Certificate of insurance being handed over at a construction job site

What General Liability Does Not Cover

General liability is important, but it does not cover every business risk. Depending on your operations, you may need additional policies.

Not usually covered by general liabilityCoverage usually needed
Employee injuriesWorkers' Compensation
Business vehicles or auto accidentsCommercial Auto
Professional mistakes or bad adviceProfessional Liability / E&O
Damage to your own building, tools, inventory, or equipmentCommercial Property or BOP
Cyber attacks or data breachesCyber Liability
Employee lawsuitsEPLI
Alcohol-related liabilityLiquor Liability
Pollution claimsPollution Liability
Higher lawsuit limitsCommercial Umbrella / Excess Liability
Property in your care, custody, or controlInland Marine / Bailee Coverage
Crime, theft, or employee dishonestyCrime / Employee Dishonesty Coverage

Coverage depends on the actual policy form, endorsements, exclusions, state, and underwriting approval.

Transportation General Liability Coverage

Transportation businesses may need general liability coverage for non-auto premises and operations exposures that are separate from commercial auto liability. Casurance can help review GL options for transportation companies, including office exposure, dispatch operations, customer and vendor visits, garage or premises exposure, contract requirements, certificates, additional insured requests, and related coverage needs.

Truckers, motor carriers, freight brokers, dispatch companies, and logistics operations
Limousine, black car, chauffeur, NEMT, paratransit, ambulette, and medical transportation services
Bus companies, charter buses, shuttles, motorcoaches, taxis, rideshare fleets, and TNC fleets
Couriers, delivery companies, last-mile delivery, moving companies, auto transport, and tow truck operations
Important: General liability does not replace commercial auto insurance. If your business owns, leases, hires, or operates vehicles, you may also need commercial auto, hired and non-owned auto, physical damage, motor truck cargo, non-trucking liability, or other transportation coverages.
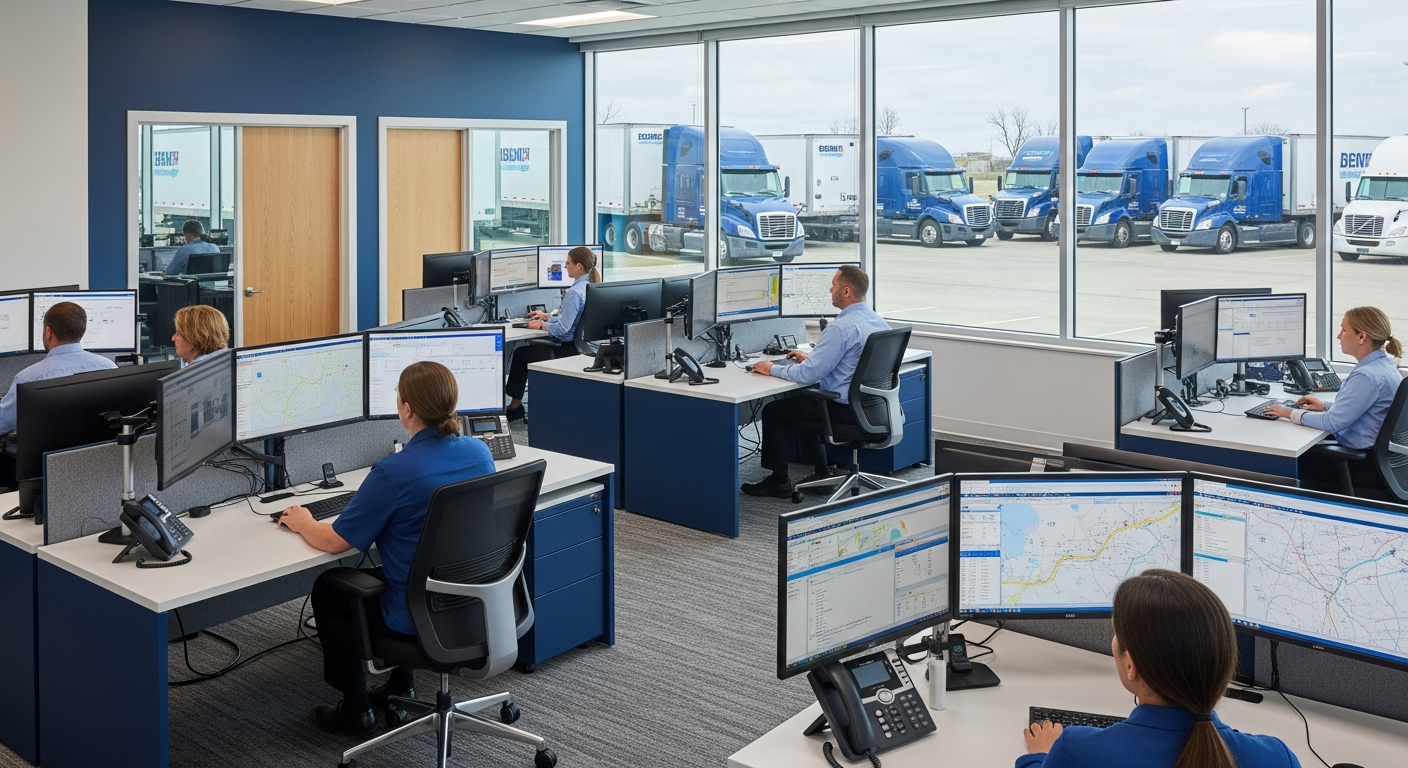
Transportation company office with dispatch operations
Commercial transportation fleet at depot

General Liability vs. Business Owner's Policy

General liability covers third-party injury, property damage, and certain advertising injury claims. A Business Owner's Policy, or BOP, usually bundles general liability with commercial property and business income coverage.

If you own equipment, inventory, furniture, fixtures, computers, tools, or lease a storefront, a BOP may make more sense than general liability alone. If your business is larger, higher risk, or needs more flexibility, a commercial package policy may be a better fit.
General Liability
  • Third-party bodily injury
  • Third-party property damage
  • Personal and advertising injury
  • Legal defense costs
  • Medical payments
  • Products-completed operations
BOP
  • General liability
  • Business property
  • Business income
  • Equipment, inventory, fixtures, and contents
  • Optional endorsements depending on the program

How Much Does General Liability Insurance Cost?

General liability insurance pricing depends on your industry, location, payroll, revenue, number of employees, prior claims, coverage limits, deductibles, certificates, endorsements, and contract requirements.

Type of business
Industry risk
Annual revenue
Payroll and employees
Location and state
Prior claims
Policy limits
Deductible
Additional insured and contract requirements
Products-completed operations exposure
Foot traffic or customer visits
Work performed away from your premises

Many small businesses request $1,000,000 per occurrence / $2,000,000 aggregate limits, but the right limit depends on your contracts, landlord requirements, project owner requirements, industry, and exposure. Some businesses also need umbrella or excess liability for higher limits.

Business owners policy with general liability and property coverage
Retail storefront protected by general liability insurance

What Information Do You Need for a General Liability Quote?

Business name and contact information
Business address and state
Description of operations
Years in business
Annual revenue
Payroll and number of employees
Prior claims history
Current insurance information if available
Desired limits
Contract or lease insurance requirements
Certificate holder details if a COI is needed
Additional insured wording if requested
Subcontractor usage for contractors
Products sold or work completed if applicable

Ready to Compare General Liability Options?

Tell us about your business and we will help you review coverage, limits, certificates, and endorsements.

Talk with Casurance: 1-888-254-0089

Frequently Asked Questions

Protect Your Business From Everyday Liability Claims

Whether you need coverage for a lease, a client contract, a project, a storefront, a contractor job, or a certificate request, Casurance can help you compare general liability options and related business insurance coverage.

Coverage depends on underwriting, policy forms, endorsements, exclusions, and state availability.

Preparing liability insurance for a City of Los Angeles contract

If your Los Angeles business is bidding on a City contract, leasing City space or applying for a City permit, send us the insurance exhibit with your quote request. The City’s published instructions refer to the coverage types and limits in the Form Gen. 146 included with the particular agreement. A limit advertised on an insurance page is not a substitute for that project’s requirements.

The City also asks that insurance evidence identify the applicable bid, contract, lease or permit number, or the project name and job-site address. Having that information ready helps connect the certificate to the right agreement. For private customers and landlords, provide their own insurance exhibit so we can review it separately.

What to send with your quote request

  • Include the awarding department, project or agreement number, work description and planned start date.
  • Send the certificate-holder instructions and any requested additional-insured endorsements for review against the proposed policy.
  • Describe work on City premises and any subcontracted operations; request review before assuming a certificate alone satisfies the agreement.